Buying an open plot can be a good option for building a home or making a long-term property investment. With development taking place across Hyderabad and surrounding areas, many buyers are exploring plotted layouts for residential and investment purposes.
However, buying land requires more than checking the location, price, road connectivity, and amenities. One important issue buyers should investigate is whether the plot is mortgaged.
A plot may be part of an approved layout and still have a mortgage, loan, or other financial claim attached to it. Therefore, proper HMDA layout verification, title verification, and document checking are important before buying land.
In this guide, we explain how to check whether a plot is mortgaged, which documents you should review, and what precautions you can take before completing the purchase.
A mortgaged plot is a property that has been offered as security for a loan or financial obligation.
For example, a landowner or developer may use land as security when obtaining finance from a bank or financial institution. Until the applicable loan is settled and the mortgage is properly released, the property may remain subject to that financial charge.
For a buyer, purchasing such a plot without checking its status can create legal and financial complications.
Before buying land, you should find answers to these basic questions:
Who is the legal owner of the property?
Is the land currently mortgaged?
Is the specific plot included in the mortgage?
Has an earlier mortgage been released?
Does the plot match the approved layout?
Are there any other registered encumbrances?
These checks can help you understand the property’s status before you invest your money.
If a property is being marketed as an HMDA-approved layout, buyers should independently verify the approval details.
HMDA layout verification involves checking whether the layout information matches the relevant approval records and whether the plot being offered corresponds with the approved plan.
During the verification process, look at important details such as:
Layout approval number
Survey numbers
Total land extent
Plot numbers
Road layout
Open spaces
Utility areas
Developer or landowner details
Mortgage-related information, where applicable
An approved layout does not automatically mean that every individual plot is free from mortgages, disputes, or other legal issues. Therefore, layout verification should be combined with complete property due diligence.
A developer or landowner may obtain financing by offering land as security to a bank or financial institution.
In a plotted development, certain plots may be identified as mortgage plots. These plots may not be freely transferable until the applicable financial obligation is settled and the mortgage is formally released.
This is why buyers should verify the specific plot number they intend to purchase.
For example, if you are interested in Plot No. 125, do not simply rely on a salesperson’s statement that the plot is clear. Check the relevant documents and records to confirm the status of Plot No. 125.
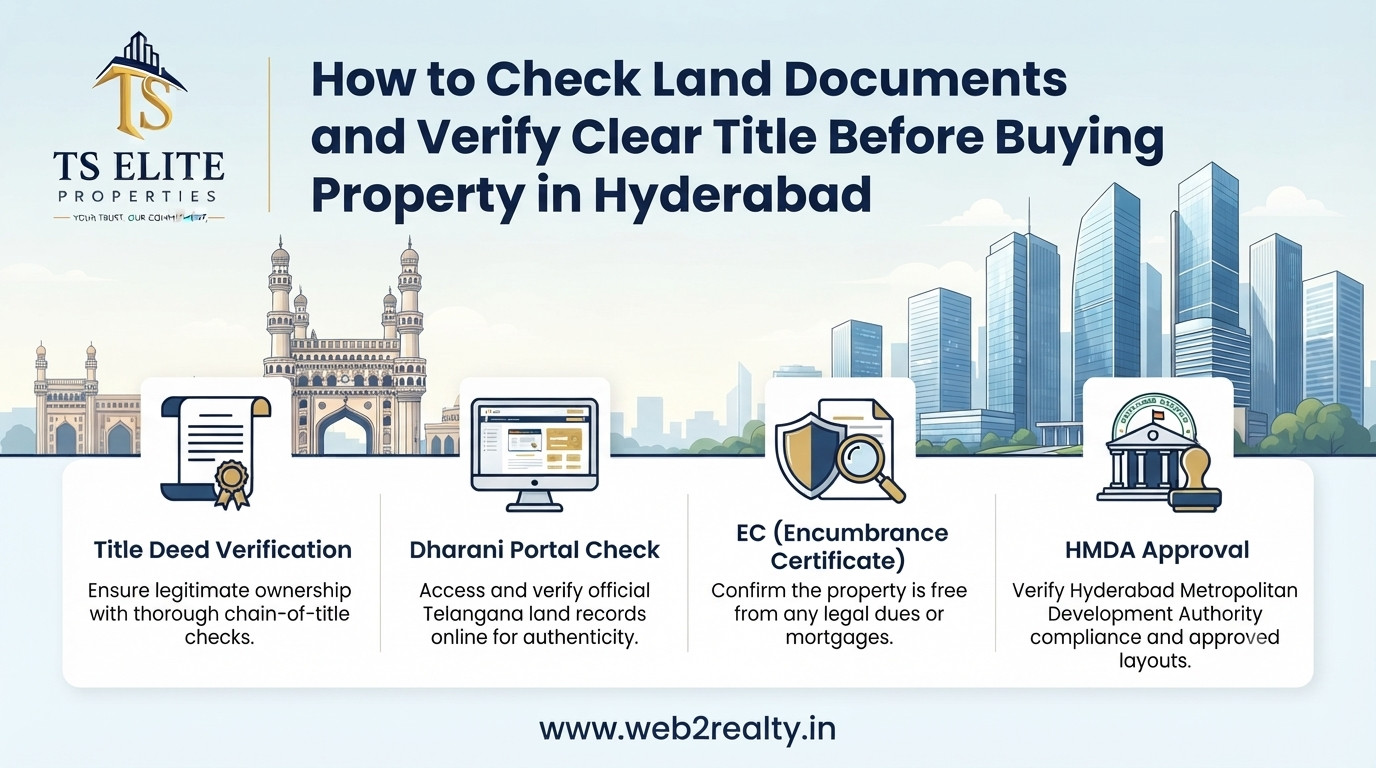
The Encumbrance Certificate (EC) is an important document to examine when checking property records.
An EC can provide information about certain registered transactions and encumbrances recorded against a property during the period covered by the certificate.
When reviewing the EC, look for entries relating to:
Mortgages
Registered loans
Property sales
Releases
Charges
Other registered transactions
Make sure the EC covers an appropriate period and relates to the correct property details.
However, an EC should not be treated as the only proof of a clear title. Some matters may not appear in the EC, so other documents and independent legal verification are also important.
The latest sale deed is another important document when buying a plot.
Compare the details in the sale deed with the property being offered to you.
Check:
Seller’s name
Survey number
Plot number
Plot area
Plot dimensions
Property boundaries
Registration details
Previous ownership details
The information should be consistent across the relevant documents.
If the plot number, survey number, area, or boundaries do not match, ask for clarification before making any payment.
A buyer should not look only at the latest sale deed. It is also important to understand how the property reached the current owner.
Previous documents, commonly known as link documents, can help establish the ownership history.
Depending on the property, these may include:
Previous sale deeds
Gift deeds
Partition deeds
Settlement documents
Inheritance records
Release deeds
Court orders, where applicable
Reviewing the ownership chain can help identify missing documents, inconsistencies, or potential claims.
An independent property lawyer can examine these documents and explain any issues that require further investigation.
This is one of the most important steps in HMDA layout verification.
If a seller or developer claims that a project has HMDA approval, verify the approval through the relevant official records.
Check whether:
The approval details are genuine
The survey numbers match
The land extent is consistent
The plot number appears in the approved plan
Plot dimensions are consistent
Roads match the approved layout
Open spaces are properly shown
The actual development follows the approved plan
Do not depend only on brochures, advertisements, WhatsApp messages, or screenshots supplied by the seller.
The approved records and property documents should support the information being presented to you.
When buying a plot in a developed layout, find out whether the specific plot is included in any mortgage arrangement.
This is an important part of HMDA layout verification and property due diligence.
Do not assume that every plot within an approved venture has the same legal status.
Ask for documentary evidence showing the status of the particular plot you want to purchase.
For example:
Plot No. 125 → Check whether Plot No. 125 is included in any mortgage or financial charge.
The seller should be able to provide appropriate documents to support the property’s status.
If the plot was previously mortgaged, ask for documents proving that the mortgage has been released.
Depending on the circumstances, relevant documentation may include:
Mortgage release deed
Release letter
Bank NOC
Loan closure documentation
Updated registration records
The exact documents required can vary depending on how the mortgage was created and released.
Do not rely only on a verbal statement such as, “The loan has already been cleared.”
Always ask for documentary evidence and have it reviewed professionally where necessary.
If a property was mortgaged to a bank or financial institution, the lender’s documentation may be important.
If the seller says that the bank has approved the sale or released the property, ask for appropriate written documentation.
The bank’s NOC or release document should clearly relate to the relevant property and transaction.
If you are unsure whether the document is sufficient, have an independent property lawyer review it before proceeding.
If an earlier mortgage has been released, do not stop after receiving a release letter.
Where applicable, check whether the relevant records have been updated to reflect the release.
This can help ensure that the property’s current documentation is consistent with the claimed mortgage status.
Your property lawyer can advise you about the documents and registrations that should be checked for the specific transaction.
Document verification should always be supported by a physical site inspection.
Visit the property and compare the actual site with the approved layout and property documents.
Check:
Plot number
Plot dimensions
Boundaries
Roads
Access points
Nearby plots
Open spaces
Existing structures
Possible encroachments
If necessary, arrange a physical survey with a qualified professional.
This can help identify differences between the documents and the property on the ground.
Not every plotted development comes under the same planning authority.
Depending on its location and applicable planning rules, a project may involve DTCP or another competent authority.
If a seller claims that a layout has DTCP approval, verify the approval independently.
Check whether the approval corresponds with:
Survey numbers
Land extent
Layout details
Plot numbers
Developer or landowner information
Whether you are conducting HMDA layout verification or checking a DTCP layout, always compare the approval information with the actual property documents.
This is an important distinction for every land buyer.
Layout approval and title verification are two different checks.
Layout approval generally relates to planning and development requirements.
Title verification focuses on ownership and the seller’s legal right to transfer the property.
Therefore, buyers should ask two separate questions:
Is the layout approved by the applicable planning authority?
Does the seller have the legal right to sell this specific plot, and is the plot free from relevant claims or encumbrances?
Both questions should be answered before completing the purchase.
Mortgage verification is only one part of property due diligence.
Buyers should also investigate whether the property is involved in any known legal dispute or claim.
Possible issues may include:
Ownership disputes
Family disputes
Partition cases
Boundary disputes
Land acquisition matters
Other litigation
A property lawyer can advise you about appropriate legal searches based on the property’s history.
If a dispute exists, understand its nature and potential impact before proceeding with the purchase.
Before buying a plot, confirm that the person selling the property has the legal authority to sell it.
If there are multiple owners, verify that the required owners are properly involved in the transaction.
For inherited property, check relevant inheritance and legal-heir documents.
If the seller is acting through a Power of Attorney, verify that the document is valid and authorizes the proposed transaction.
These checks can help reduce ownership-related problems later.
One common mistake buyers make is paying a large advance because the seller says that the property is in high demand.
It is better to complete the important checks first.
Before making a significant payment:
Verify ownership.
Check the Encumbrance Certificate.
Review the link documents.
Complete HMDA layout verification or the applicable planning-authority verification.
Check the mortgage status.
Verify mortgage release documents, if applicable.
Inspect the property physically.
Obtain independent legal advice.
Taking a little extra time before paying can help you identify potential problems early.
Use this simple checklist before buying a plot:
| Document / Check | What to Verify |
|---|---|
| Ownership | Current owner’s legal title |
| Sale deed | Plot number, area and boundaries |
| Link documents | Previous ownership history |
| Encumbrance Certificate | Registered transactions and encumbrances |
| Layout approval | Approval details and survey numbers |
| Plot number | Match with approved layout |
| Mortgage status | Whether the specific plot is mortgaged |
| Release documents | Proof of mortgage release, if applicable |
| Bank NOC | Lender’s confirmation, where applicable |
| Land records | Relevant official records |
| Litigation | Potential legal disputes |
| Site inspection | Boundaries, roads and physical condition |
| Legal opinion | Independent lawyer’s review |
Buyers can reduce unnecessary risks by avoiding a few common mistakes.
A project brochure is a marketing document. Always verify important claims against relevant records.
The ownership history can be important. Review the relevant link documents as well.
Planning approval and ownership verification are separate matters.
Always check whether the specific plot has been mortgaged or previously mortgaged.
Important claims about title, mortgage release, approvals, and ownership should be supported by documents.
Take sufficient time to complete your due diligence before making a substantial financial commitment.
Buying land requires careful verification. Price, location, connectivity, and development potential may be important considerations, but proper documentation should come first.
HMDA layout verification can help buyers confirm whether a layout and its relevant details correspond with the applicable approval records. However, it should be only one part of the overall verification process.
Before purchasing a plot, check the title, link documents, Encumbrance Certificate, mortgage status, applicable approvals, seller’s authority, and physical property details.
Most importantly, verify the specific plot you intend to buy rather than assuming that every plot in a layout has the same legal status.
When there is uncertainty, consult an independent property lawyer before signing an agreement or making a substantial payment.
Planning to buy an open plot in Hyderabad or nearby growth corridors?
At Web2Realty, we believe buyers should have access to clear property information before making an important investment decision.
Explore available plot options, understand the location and documentation, compare suitable properties, and arrange a site visit before proceeding.
Looking for open plots in Hyderabad? Contact Web2Realty today to discuss your requirements and explore available property options.
Check the documents. Verify the layout. Understand the title. Then make an informed property decision.
HMDA layout verification is the process of checking whether a layout’s approval details correspond with the relevant records and whether the survey numbers, land extent, plot numbers and other details match the property being offered.
Start by checking the Encumbrance Certificate and relevant property documents. For a plotted development, also check whether the specific plot number is included in any mortgage arrangement and ask for appropriate lender release documents if the mortgage has been cleared.
No. Layout approval and mortgage status are separate matters. Buyers should independently verify whether the specific plot has a mortgage or other relevant encumbrance.
Important documents may include the sale deed, link documents, Encumbrance Certificate, approved layout plan, applicable land records, mortgage or release documents, and other relevant approvals.
A mortgage release document provides evidence that a previously created mortgage or financial charge has been released, subject to the circumstances of the transaction. It should be reviewed carefully before proceeding.
A transaction involving a mortgaged property requires careful legal and financial handling. The buyer should understand the lender’s rights and ensure that the mortgage is properly released or otherwise dealt with before acquiring the property.
Checking the plot number helps confirm that the exact property being offered matches the approved layout and supporting documents. It can also help identify whether the plot has a different status from surrounding plots.
No. An EC is an important document, but it does not replace complete legal due diligence. Buyers may also need to check title documents, link documents, applicable land records, approvals, litigation and the physical property.
An independent property lawyer can review the title, ownership history, encumbrances, mortgage documents and other relevant records. Professional legal advice can be particularly useful when the documentation is complex.
A common mistake is relying only on seller statements or marketing material. Buyers should independently verify the specific plot, its documents, approval status, ownership and mortgage position before making a significant financial commitment.
This version is designed to be more readable for website visitors, while keeping the primary keyword natural rather than forcing it into every paragraph.